The decision to open a second or third demat account deserves a bit more thought than simply picking whichever broker has the most appealing advertisement that week. While holding multiple accounts offers genuine advantages, getting the most out of this approach depends on checking a handful of practical details beforehand, so the new account actually serves its intended purpose rather than becoming an unnecessary addition to manage. Here’s a thorough look at what’s worth confirming before you open another account.
Clarify the Specific Purpose First
Before anything else, it genuinely helps to be clear on exactly why you want another account, since this single decision shapes everything that follows.
- Define what this new account will actually be used for — active trading, a specific financial goal, testing a new broker, or holding a different asset type — rather than opening it with only a vague sense that having more than one account is generally useful.
- Confirm this purpose is genuinely distinct from what your existing account already handles well, since opening a new account for something your current one already does perfectly fine adds complexity without real benefit.
- Write this purpose down, even informally, since having a clear statement of intent makes it much easier to evaluate later whether the account is still serving you well.
- A clearly defined purpose also helps you choose the right broker for this specific account, since different platforms suit different activities.
Review the Full Cost Structure of the New Account
Every additional demat account comes with its own set of charges, and understanding these clearly before opening helps you judge whether the benefit genuinely outweighs the cost.
- Check the Annual Maintenance Charge for the specific broker you’re considering, since this is a cost you’ll pay every year regardless of how actively you use the account.
- Confirm whether your expected portfolio size for this account qualifies for BSDA benefits, which can reduce or waive AMC for smaller holdings under SEBI’s framework.
- Understand the brokerage structure, particularly if this account is meant for a different style of investing than your existing one, since a broker ideal for delivery trading might charge quite differently for intraday or F&O activity.
- Factor in Depository Participant charges, which apply whenever you sell from this account, adding a small but real cost each time you do so.
Confirm the Broker Genuinely Suits the Intended Purpose
Since the whole point of opening another account is usually to access something your current setup doesn’t offer well, it’s worth verifying this specific strength actually exists.
- Research the broker’s specific features relevant to your purpose — charting tools for active trading, mutual fund interface quality for SIP investing, or research depth for informed decision-making — rather than assuming based on general reputation alone.
- Read recent reviews focused specifically on the feature you care about, since a broker’s overall rating doesn’t always reflect how well it performs in the one area that matters most for this particular account.
- Try the broker’s demo or explore its app before committing, where possible, to get a genuine sense of whether it delivers what you’re expecting.
- Confirm the broker’s customer support quality, particularly if you’re less familiar with this platform, since a smooth onboarding experience matters more when you’re managing multiple relationships simultaneously.
Plan for the Administrative Overhead
Every additional account brings a small amount of ongoing management responsibility, and it’s worth being honest about whether you’re prepared for this before adding to your setup.
- Consider how you’ll track this account alongside your existing ones, whether through a spreadsheet, a portfolio tracking app, or simply a disciplined habit of reviewing each account’s statement periodically.
- Think through your tax filing process, since this new account’s transactions will need to be gathered and reported alongside everything else at tax time, adding a bit more compilation work each year.
- Decide how you’ll manage nominee details, remembering that nomination needs to be set individually for every account you open, with no automatic carryover from your existing accounts.
- Be realistic about your own capacity to stay organized, since the benefits of multiple accounts only materialize if you actually maintain a clear structure rather than letting accounts become scattered and forgotten.
Check the KYC and Documentation Process
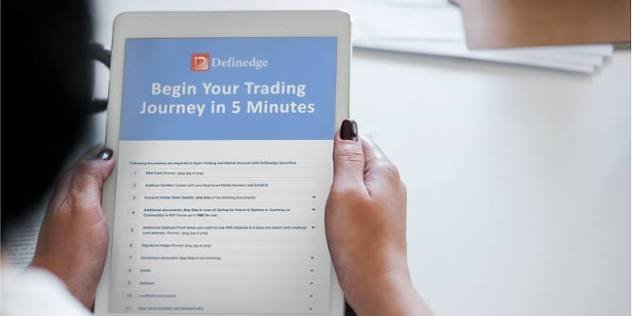
While opening an additional account is generally faster than your very first one, it’s still worth understanding exactly what’s involved before you begin.
- Confirm your Aadhaar is still linked to your current, active mobile number, since this remains essential for completing e-KYC regardless of how many accounts you’ve opened before.
- Check whether your existing KYC details will be referenced automatically through the central KYC Registration Agency system, which can sometimes speed up this new application.
- Gather your documents just as carefully as you did for your first account, since a blurry PAN photo or a name mismatch causes the same delays regardless of how experienced you already are with the process.
- Decide your nominee for this specific account in advance, so this step doesn’t become an unexpected pause during an otherwise quick application.
Think Through How You’ll Fund the New Account
Since each demat account links to its own bank account for settlement, it’s worth planning this connection thoughtfully.
- Decide which bank account you’ll link, considering whether you want this new account’s transactions to flow through your existing primary bank account or a separate one dedicated to this specific investing purpose.
- Confirm the name on your chosen bank account matches your PAN and Aadhaar exactly, since this consistency affects how smoothly the account verification process goes.
- Plan your initial funding amount, particularly if this account is meant to support a specific, defined goal, so you’re starting with a clear sense of your contribution plan rather than figuring it out after activation.
- Consider whether you’ll need to transfer funds between your own bank accounts regularly to keep this new demat account properly funded for its intended activity.
Assess Whether Consolidation Might Serve You Better
Before finalizing the decision to open another account, it’s worth genuinely considering whether your goal could be achieved more simply within your existing setup.
- Check whether your current broker already offers the feature or benefit you’re seeking elsewhere, since sometimes a quick look at your existing platform’s full feature set reveals you already have access to what you thought required a new account.
- Consider whether a simple internal reorganization — like using tags, folders, or separate watchlists within your existing account — could achieve the same clarity you’re hoping a second account will provide.
- Weigh the ongoing AMC and administrative cost of a new account against the actual, specific benefit it brings, being honest about whether this trade-off genuinely makes sense for your situation.
- Remember that opening an account is easier than closing or consolidating one later, so a bit of extra consideration now prevents unnecessary accounts from accumulating over time.
A Simple Pre-Opening Checklist
Running through this short list before submitting a new application helps ensure you’ve genuinely thought this decision through.
- A clear, specific purpose for the new account, distinct from what your existing account already handles.
- A full understanding of the AMC, brokerage and DP charges you’ll be taking on.
- Confirmation that the broker genuinely excels at the specific feature motivating this decision.
- A plan for tracking this account alongside your existing ones.
- Your nominee details and bank account decided in advance.
- A final, honest check on whether consolidation within your current setup might serve the same purpose.
Frequently Asked Questions
Q1. Is it worth opening a new demat account just because a broker is offering a limited-time discount or bonus?
A promotional offer alone isn’t a strong enough reason on its own — it’s worth checking whether the broker genuinely fits a specific purpose you need, since an account opened purely for a short-term incentive often ends up as an unused addition once the promotional period ends.
Q2. Should I check anything specific if I’m planning to use the new account for a completely different asset type, like commodities?
Yes, it’s worth confirming the broker genuinely supports that specific segment well, including checking their commodity-specific research tools, margin requirements and brokerage rates, since not every broker that excels at equity trading offers the same strength in commodities or currency derivatives.
Q3. How do I know if I actually need a new account or if my existing broker can meet my new requirement?
Spend some time exploring your existing broker’s full feature set and settings before assuming you need a new account, since many platforms have added features over time that investors aren’t always aware of, and a quick check can sometimes save you from an unnecessary new account.
Q4. What’s the most commonly overlooked detail when people open additional demat accounts?
Nominee details are frequently overlooked, since people often assume their existing nomination somehow carries over, when in fact every new account requires its own separate nomination decision, which is worth setting correctly from the start rather than revisiting later.