Charitable trusts, religious institutions, family trusts and other trust structures that want to invest their funds in the stock market need a demat account opened specifically in the trust’s own name, separate from the personal holdings of any trustee managing it. This keeps the trust’s investments clearly attributed to the entity itself, supporting proper governance, accurate tax treatment and transparent record-keeping for everyone with a stake in how the trust’s funds are managed. Here’s a complete look at how a trust demat account works and what’s needed to open one.
What a Trust Demat Account Actually Is
This account type recognizes a trust as a distinct legal entity, separate from the individuals who manage or benefit from it.
- A trust demat account is opened in the name of the trust itself, using the trust’s own PAN, making the trust the legal holder of everything invested through the account.
- It operates through the same depository system, either NSDL or CDSL, as any other demat account, simply structured around the specific legal and governance requirements that apply to trusts.
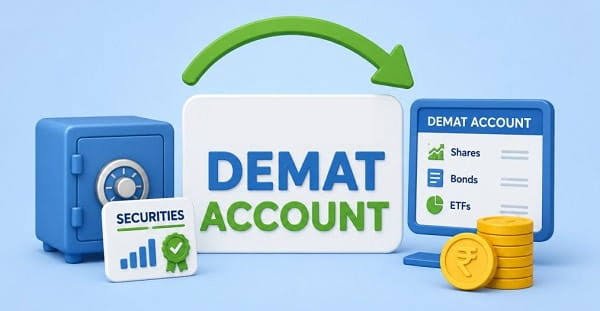
- The account can hold the full range of securities — equity shares, mutual funds, bonds and ETFs — allowing a trust to build and manage an investment portfolio in pursuit of its stated objectives.
- This structure applies to various types of trusts, including charitable trusts, religious trusts, family or private trusts, and trusts set up for specific purposes like education or healthcare.
Why Trusts Need Their Own Demat Account
Since a trust exists as a distinct legal entity, its investment activities need to be kept clearly separate from the personal finances of anyone involved in managing it.
- A demat account in the trust’s name holds investments under the trust’s own PAN, rather than attributing them to any individual trustee personally, keeping the trust’s finances transparent and properly documented.
- This separation supports accurate tax reporting, since income and capital gains earned through the trust’s investments are taxed according to the trust’s own applicable tax treatment, distinct from any trustee’s personal income.
- It provides clear accountability for beneficiaries, since the trust’s investment activity is documented under its own name rather than mixed into a trustee’s personal portfolio where it could become difficult to track.
- For charitable and religious trusts specifically, this separation is often essential for maintaining the tax-exempt status and public trust that these organizations depend on.
Who Operates the Account
A trust’s demat account functions through trustees who are formally authorized to act on the trust’s behalf.
- The trust deed specifies who the trustees are and outlines their authority to manage the trust’s assets, including any investments made through a demat account.
- Depending on the trust deed’s specific terms, either a single trustee may be authorized to operate the account independently, or multiple trustees may need to jointly authorize transactions.
- Trustees complete their own KYC verification — PAN, Aadhaar and identity confirmation — since they’re the individuals being verified to transact on the trust’s behalf.
- If a trustee changes, due to resignation, death, or completion of their term, the trust needs to formally update this with the broker, providing documentation that reflects the new trustee structure.
Documents Required to Open a Trust Demat Account
Opening this account involves documentation specific to the trust’s legal structure, alongside verification of its trustees.
- The Trust Deed, the foundational legal document establishing the trust, its objectives, and the names and authority of its trustees.
- The trust’s own PAN card, which anchors its tax identity, separate from the PAN of any individual trustee.
- A registration certificate, where applicable, confirming the trust’s registration with the relevant authority, particularly relevant for charitable or religious trusts.
- KYC documents for all trustees, following the standard PAN, Aadhaar and identity verification process required of any individual applicant.
- A resolution or authorization letter from the trustees, specifically authorizing the opening and operation of the demat account.
- The trust’s bank account details, which need to be in the trust’s own name for linking to the demat account.
How Transactions Work in a Trust Account
Day-to-day operation of a trust demat account follows a structure centered on the authorized trustees and the terms laid out in the trust deed.
- Authorized trustees place buy and sell orders on behalf of the trust, using credentials set up specifically for this purpose, following whatever authorization structure the trust deed and broker have on record.
- Investment decisions are generally expected to align with the trust’s stated objectives, as outlined in the trust deed, since trustees have a fiduciary responsibility to manage the trust’s assets appropriately.
- Dividends and other corporate action benefits from the trust’s investments are credited to its linked bank account, becoming part of the trust’s overall financial resources.
- All transactions should be reflected clearly in the trust’s financial records, supporting transparent reporting to beneficiaries and any regulatory bodies the trust is accountable to.
Tax Treatment of Trust Investment Income
How a trust’s investment income is taxed depends significantly on the type of trust and its specific registration status.
- Charitable and religious trusts registered under applicable provisions may be eligible for tax exemptions on their income, including investment income, provided they meet the specific conditions required to maintain this status.
- Private or family trusts are generally taxed according to rules that depend on the trust’s specific structure, whether it’s a discretionary or non-discretionary trust, affecting how income is attributed and taxed.
- Maintaining clear records of all investment income and its use is particularly important for charitable trusts, since this supports their continued eligibility for any tax-exempt status they hold.
- Given how much tax treatment depends on the trust’s specific type and registration, consulting a chartered accountant familiar with trust taxation is genuinely worthwhile when setting up and managing this account.
Governance Considerations Specific to Trusts
Since a trust’s purpose and obligations differ from a typical business or individual, a few additional governance points are worth understanding.
- Trustees have a fiduciary duty to manage the trust’s investments prudently, in line with the objectives laid out in the trust deed, rather than treating the account as a vehicle for personal financial gain.
- Many trusts, particularly charitable ones, may have specific restrictions on the types of investments permitted, so it’s worth reviewing the trust deed carefully before making investment decisions through the demat account.
- Regular reporting to beneficiaries or regulatory bodies may be required, depending on the trust’s nature, making clear and organized transaction records essential.
- Any significant investment decision may require documented approval from all trustees, depending on the trust deed’s specific governance requirements.
Differences From Other Account Types
Understanding how a trust account compares to other entity-based structures helps clarify exactly where it fits.
- Unlike a corporate demat account, which is governed by the Companies Act and operates through authorized signatories appointed by a board resolution, a trust account is governed by the trust deed and operates through its named trustees.
- Unlike an HUF demat account, which represents a family unit under Hindu law, a trust can be established for a much broader range of purposes, including charitable, religious, or private family objectives, under a separate legal framework.
- The tax treatment of a trust can vary considerably more than other entity types, depending specifically on whether it’s charitable, religious, or private, unlike the more uniform tax rules applied to individual or corporate accounts.
- Documentation requirements are centered on the trust deed specifically, making this the single most important document in the entire account opening process, more so than any other single document for most other account types.
Practical Tips for Managing a Trust Demat Account
A few habits help keep this account well-organized and aligned with the trust’s broader obligations.
- Keep the trust deed and any amendments readily accessible, since these will be referenced whenever trustee changes or account updates are needed.
- Maintain detailed records of all investment transactions, supporting transparent reporting to beneficiaries and simplifying annual tax filing.
- Review investment decisions against the trust deed’s objectives periodically, ensuring the trust’s activities remain aligned with its stated purpose.
- Coordinate closely with a chartered accountant familiar with trust taxation, given how much the tax treatment can depend on the specific type and registration of the trust.
Frequently Asked Questions
Q1. Can a charitable trust invest in the stock market while still maintaining its tax-exempt status?
Yes, charitable trusts can generally invest in permitted securities while maintaining their tax-exempt status, provided they comply with the specific conditions and investment restrictions applicable to their registration, so it’s worth reviewing these conditions carefully with a tax professional before investing.
Q2. What happens to a trust’s demat account holdings if a trustee resigns or passes away?
The trust’s holdings remain entirely intact, since the investments belong to the trust itself rather than to any individual trustee, and the trust simply needs to update the broker with documentation reflecting the new or remaining trustees authorized to operate the account.
Q3. Is a trust demat account suitable for a small family trust, or is this only for large charitable organizations?
Trust demat accounts work for trusts of any size and purpose, including small family or private trusts, as long as the trust has a properly executed trust deed and the required documentation, making this accessible regardless of the trust’s scale.
Q4. Do all trustees need to approve every single transaction in the trust’s demat account?
This depends entirely on what the trust deed specifies — some trust deeds authorize a single trustee to operate the account independently, while others require joint approval from multiple trustees for transactions, so it’s worth reviewing this specific provision before opening the account.